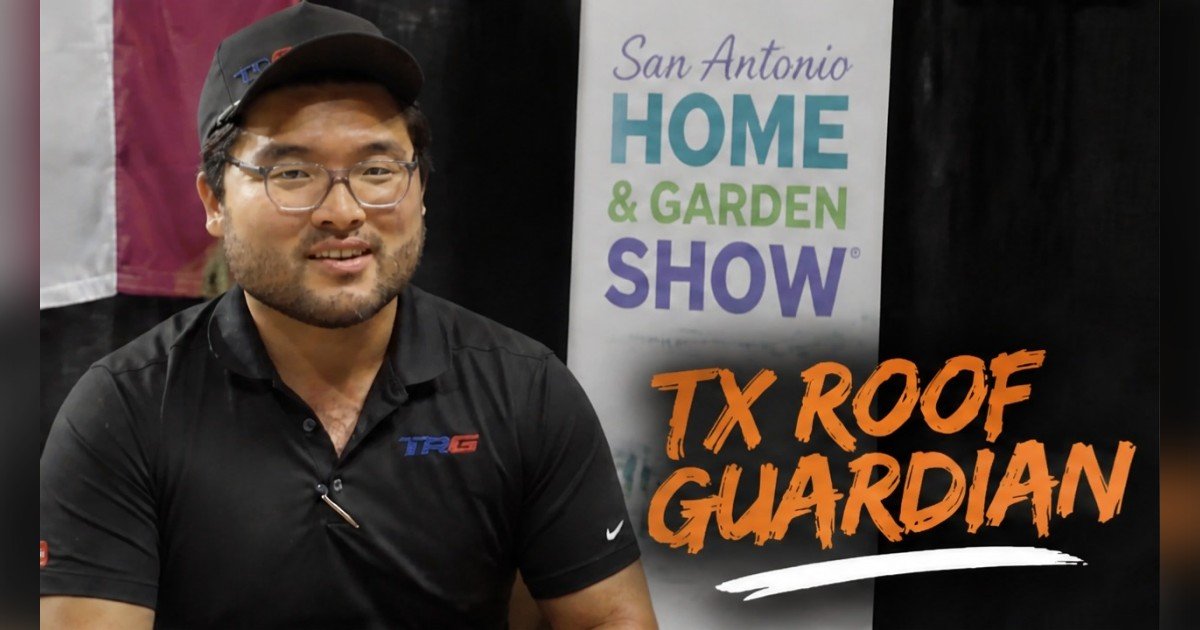
Why 60-70% of Roof Claims Get Denied, and How Texas Homeowners Fight Back
Jasper Shin of Texas Roof Guardians joins Justin McKenzie at the San Antonio Home and Garden Show to expose why insurers deny most roof claims, why the average file is short $3,000-$5,000, and why solar on a 7-year-old roof is a leak waiting to happen.

San Antonio, TX (Newsworthy.ai) Tuesday Nov 3, 2026 @ 9:27 AM CST
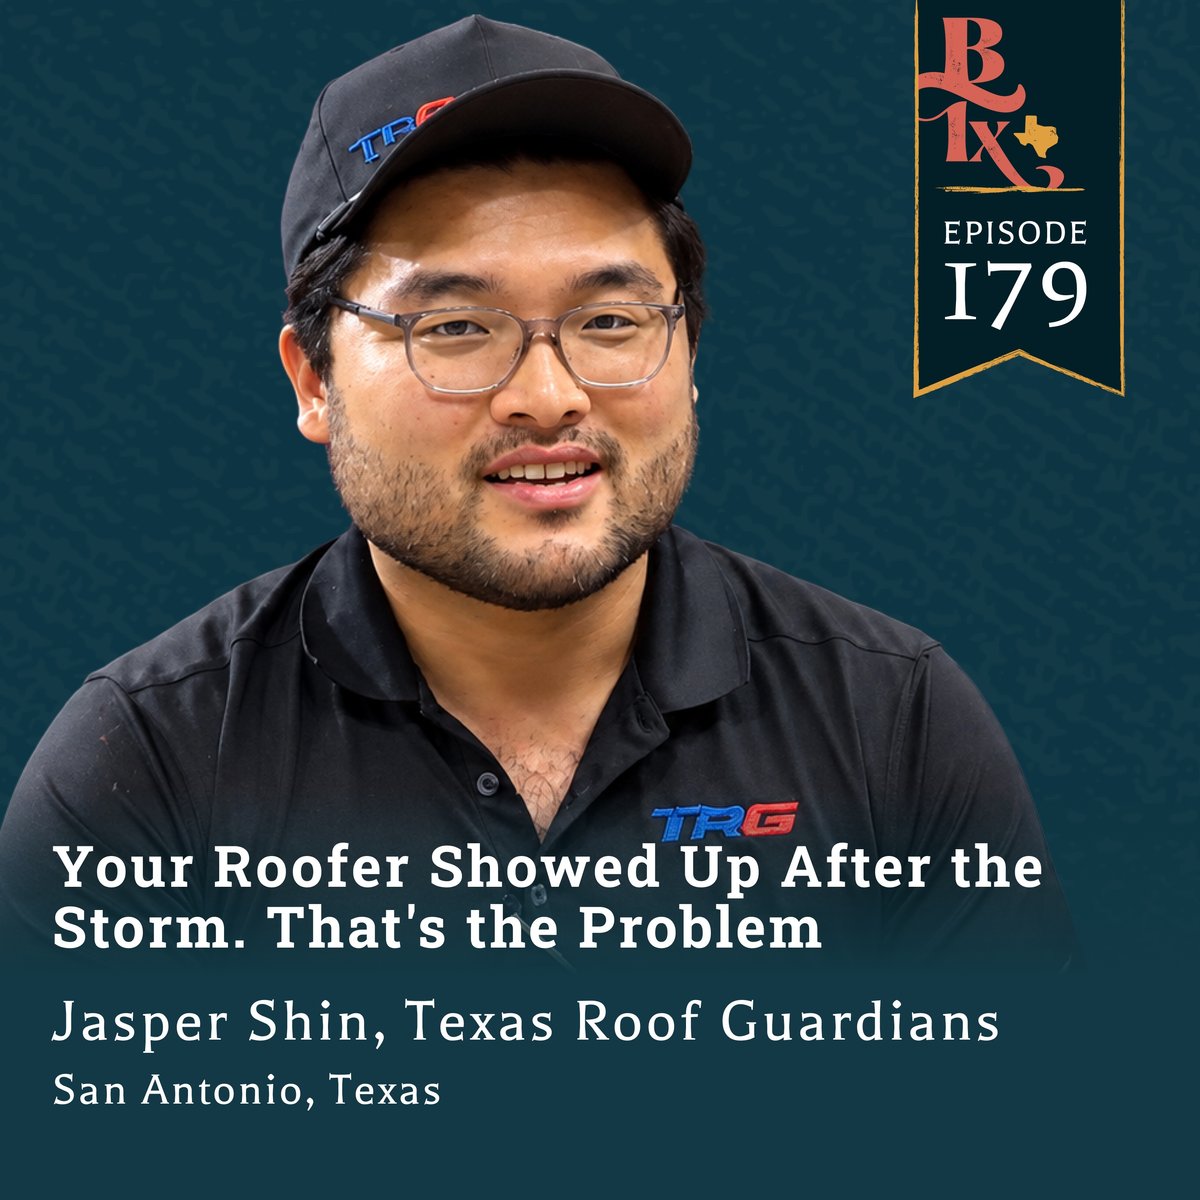
The Building Texas Show — Your Roofer Showed Up After the Storm. That's the Problem
“The insurance is incentivized to not pay you to say you don't have damage. Around 60 to 70% of claims get denied. And it's not because they should be.”
The latest episode of The Building Texas Show, titled Your Roofer Showed Up After the Storm. That's the Problem, published September 15, 2026, features host Justin McKenzie sitting down with Jasper Shin of Texas Roof Guardians on the floor of the San Antonio Home and Garden Show. The conversation lands as San Antonio absorbs the aftermath of five hail storms in a single year and Hill Country homeowners rediscover leaks after historic rains. At the center of the discussion: why 60 to 70 percent of roof insurance claims get denied, and what Texas homeowners can do before they ever pick up the phone to their carrier.
Shin walks listeners through the mechanics of a modern roof claim and the traps that quietly cost homeowners thousands. Topic threads include:
The Building Texas Show — Your Roofer Showed Up After the Storm. That's the Problem
“The insurance is incentivized to not pay you to say you don't have damage. Around 60 to 70% of claims get denied. And it's not because they should be.”
- The full-property inspection covering windows, screens, gutters, siding and fences, not just shingles
- The three-reinspection rule most homeowners never learn they have
- Xactimate supplements and how to force fair-market pricing from an adjuster
- The mortgage-company check split that stalls repairs
- Why installing solar on a roof older than seven years is, in Shin's words, asking for leaks
Shin is blunt about the incentive structure homeowners are up against. "The insurance is incentivized to not pay you to say you don't have damage," he tells McKenzie, adding that the average claim file is missing $3,000 to $5,000 in legitimate damages. He describes cases where supplements have added $10,000, $15,000, even $30,000 to approved claims. He also warns homeowners about a single innocent question from a carrier: "Well, why did you wait?" Answer it wrong, Shin explains, and insurers can invoke the mitigation clause buried in most policies and deny the claim for negligence before an adjuster ever climbs a ladder.
The episode goes deep on the storm-chaser problem plaguing Texas metros from San Antonio and Austin to Dallas and Houston. Shin explains why Texas Roof Guardians chose to stay local rather than chase four-inch hail in Chicago, Montana and the Carolinas, and how homeowners can validate a contractor through GAF, Owens Corning and Atlas certifications, a legitimate Google Business Profile, and Better Business Bureau standing. He details a Stone Oak client whose insurer quietly converted her policy at the 10-year mark, leaving her $15,000 short on a $25,000 replacement, and outlines the company's free policy review, free biannual inspection subscription, and white-glove service from Kerrville to Seguin, up and down I-35, and into Pearsall, Uvalde and Victoria.
About The Building Texas Show
The Building Texas Show, hosted by Justin McKenzie, spotlights the operators, tradespeople and entrepreneurs shaping Texas communities. Each episode digs into the practical realities of building, protecting and growing a home or business in the Lone Star State, with candid conversations that arm listeners with information they can act on. This episode is available now wherever podcasts are heard, and at txroofguardians.com or 726-244-5844 for a free policy review.
Frequently Asked Questions
- Why do 60 to 70 percent of roof insurance claims get denied?
- Jasper Shin explains that insurers are incentivized not to pay, and they know most homeowners don't understand how to request a re-inspection without opening a new claim. Many homeowners also avoid filing altogether out of fear their rates will rise, even though carriers legally cannot raise rates for acts of God like hail, wind, tornadoes and hurricanes in a designated catastrophe area.
- What is the three-reinspection rule Shin references?
- Shin says homeowners legally have the right to three re-inspections within the same claim before having to open a new one. It is a professional way to disagree with an adjuster's ruling, avoid stacking multiple claims in your history, and get closer to approval without additional cost to the homeowner.
- Why is putting solar on an older roof a problem?
- According to Shin, if a roof is more than seven years old, homeowners should not be installing solar on it because they are essentially asking for leaks. He also notes that when solar companies go out of business, homeowners are left without service, though insurance will typically pay for detach-and-reset if ownership of the panels is documented.
- What is an Xactimate supplement and why does it matter?
- Xactimate is the third-party software insurance carriers use for fair-market pricing, and a supplement adds items the insurance originally missed. Shin says the average claim is short $3,000 to $5,000, and using the insurer's own Xactimate pricing has helped Texas Roof Guardians add $10,000, $15,000, even $30,000 to approved claims.
- How can homeowners tell a legitimate local roofer from a storm chaser?
- Shin recommends checking for manufacturer certification logos like GAF, Owens Corning or Atlas on the company's website, a local Google Business Profile, a legitimate website, and Better Business Bureau standing. He also suggests asking how long the company has been in business, since a 10-year labor warranty is meaningless from a contractor who has not been around that long.
- What does the free biannual inspection subscription include?
- Texas Roof Guardians offers a free subscription that uses an automated weather-monitoring system to alert the team when a storm hits a client's area. They then reach out to schedule an inspection and create timestamped photo documentation, which counters an insurer's common defense that damage is old or pre-existing wear and tear.
- Why does the mortgage company end up on the insurance check?
- Shin explains that with a replacement cost value policy, the insurer first deducts the deductible, then splits the remainder into an upfront payment and a depreciation holdback paid on the back end. The upfront check typically names the mortgage company, and each lender requires different documentation and mailing procedures, which is why Texas Roof Guardians helps homeowners navigate that release process.
Media Contact
Other Recent News for The Building Texas Show
- San Antonio Couple Bets on Local Window Shop After $300 Energy Bill Gap
- Texas County Judges Get a Waste-to-Energy Pitch From LOCOAL
- Hill Country Telephone Co-op Backs Its Students, From Friday Night Lights to Venture Fest
- San Antonio, the Hidden Giant: Dr. Lina Rugova on Putting the City on the Global Shortlist
- Inside Hill Country Venture Fest: How Central Texas Electric Co-op Powers Student Pitches